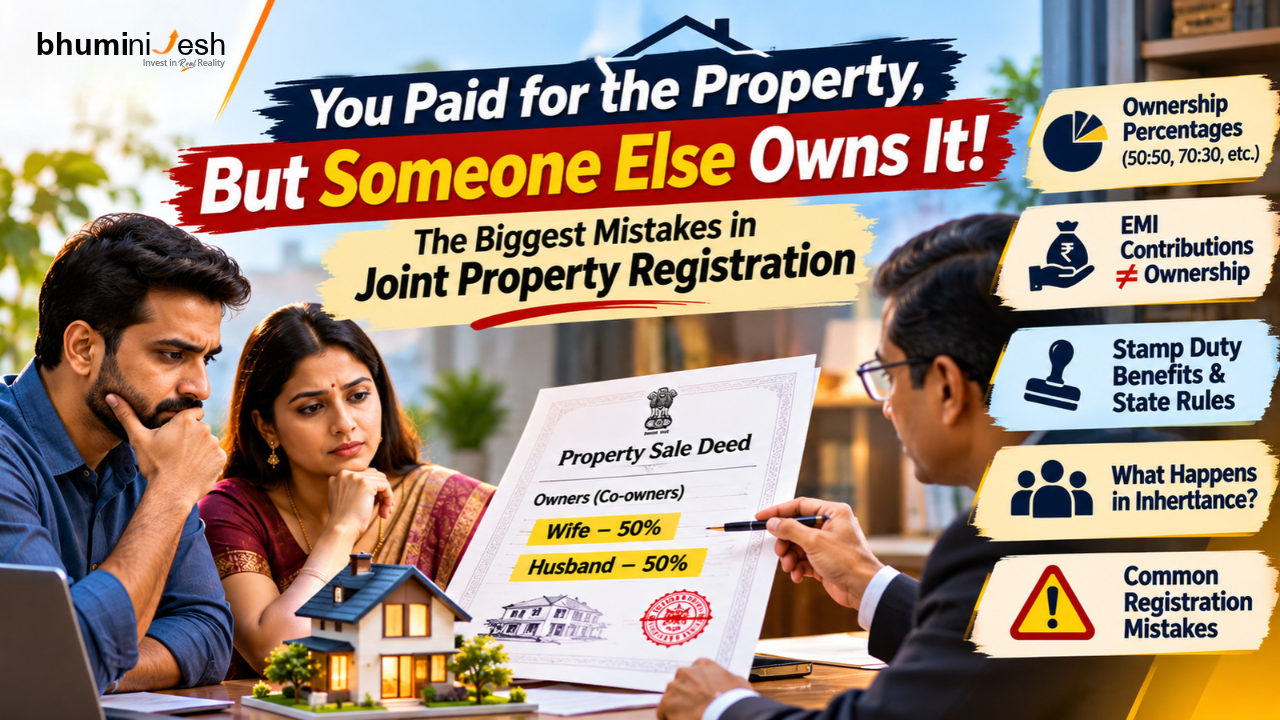
Introduction: You Paid for the House. But Whose Name Is on the Ownership Documents?
Imagine you spend ₹80 lakh purchasing an apartment. You arrange the down payment, pay the monthly home loan instalments and manage most of the expenses. But when the sale deed is registered, the property is placed in the names of your spouse, parent or another family member.
Years later, a disagreement arises.
You believe you own the property because you paid for it. The other person points to the registered sale deed, which identifies them as an owner. The bank’s loan documents show both of you as borrowers, but they do not necessarily establish the ownership shares you assumed.
Suddenly, a simple family purchase becomes a complicated legal and financial question.
Who actually owns the property: the person who paid for it, the person whose name appears on the sale deed, or both?
This is one of the most misunderstood aspects of buying real estate in India.
Many buyers focus on the property price, location, home loan interest rate and stamp duty. They do not spend enough time deciding how ownership should be recorded.
That mistake can create problems during resale, separation, inheritance, loan repayment disputes or the death of an owner.
The fundamental lesson is that payment, borrowing and legal ownership are three different things. They may overlap, but they should never be assumed to mean the same thing.
This guide explains how joint ownership works, why EMI contributions do not automatically determine ownership, how ownership percentages should be documented, and what buyers should check before registering a property.
1. The Sale Deed Matters More Than Your Assumptions
The sale deed is one of the most important documents establishing ownership of a purchased property. It identifies the buyer or buyers and records the transaction through which the property is transferred.
Consider three examples:
-
A husband pays the entire purchase price, but the sale deed names only his wife.
-
A wife and husband both contribute money, and both are named as buyers.
-
A father pays the down payment, while his son and daughter are named as co-owners.
These situations may look financially similar, but their legal consequences can be very different.
A person who contributes money towards a purchase does not automatically become a registered co-owner simply because they made the payment. Equally, a person named as a buyer cannot be assumed to have no ownership merely because they did not personally pay an instalment.
The exact legal position depends on the sale deed, the source and purpose of funds, the contractual arrangements, applicable property and tax laws, and the facts of the transaction.
The mistake: Buyers decide whose name to put on the deed casually, often assuming that the person paying the money will always have the final say.
The better approach: Decide the intended ownership structure before registration and make sure the documents accurately reflect it.
2. Joint Ownership Does Not Automatically Mean 50:50 Ownership
One of the most common misunderstandings is that when two people buy a property together, each automatically owns 50%.
That is not a safe assumption.
Section 45 of the Transfer of Property Act, 1882 deals with joint transfers for consideration. Broadly, where buyers pay from separate funds, their interests may correspond to the proportions of consideration they advanced, unless there is a contract to the contrary. Where evidence of contributions or their interests is absent, the section provides for a presumption of equal interests. IndiaCode+1
However, buyers should not rely on a general statutory rule instead of clearly recording their intended shares.
Example: Different contributions
Suppose two brothers purchase a property for ₹1 crore.
|
Particulars |
Brother A |
Brother B |
|---|---|---|
|
Down payment |
₹30 lakh |
₹10 lakh |
|
Other purchase contribution |
₹20 lakh |
₹40 lakh |
|
Total contribution |
₹50 lakh |
₹50 lakh |
|
Intended ownership |
50% |
50% |
Here, their financial contributions and intended shares are equal.
Now consider another example:
|
Particulars |
Brother A |
Brother B |
|---|---|---|
|
Total contribution |
₹70 lakh |
₹30 lakh |
|
Intended ownership |
70% |
30% |
If the buyers intend a 70:30 arrangement, they should ensure that the sale deed clearly records the respective undivided shares and that the supporting financial records are consistent.
A vague statement such as “jointly owned” may create avoidable confusion later.
Practical lesson: Record the ownership percentage explicitly. Do not leave an important financial arrangement to assumptions or family understanding.
3. You Pay the EMI, But Are You the Owner?
This is one of the most important issues in joint property purchases.
Many couples take a home loan together. One person may earn more and pay most of the EMI, while the other is included as a co-applicant or co-owner.
Buyers sometimes assume that the person paying the EMI owns the corresponding percentage of the property.
That is not necessarily correct.
There are three different roles to understand:
-
Owner or co-owner: A person whose legal interest in the property arises from the title documents or another legally recognised transfer.
-
Borrower or co-borrower: A person responsible for repayment under the loan agreement.
-
EMI contributor: A person whose bank account or funds are used to make loan payments.
A person can be a borrower without being a co-owner. A co-owner may also have a legal share even if another person pays more of the loan instalments.
Example: Husband pays the entire EMI
A husband and wife jointly purchase an apartment. The sale deed records equal ownership shares. The husband subsequently pays all the EMIs from his salary.
Can he automatically claim that the wife owns nothing?
No. The EMI payment arrangement does not, by itself, rewrite the registered ownership structure. The legal consequences must be assessed under the deed, applicable law and the facts. In particular, the husband should not assume that his payment records automatically cancel the wife’s recorded share.
A Delhi High Court judgment in Sangeeta Gera v. Sanjeev Gera (2025) illustrates the risks of claiming exclusive ownership of jointly held property merely because one spouse provided the purchase consideration. The court rejected the husband’s claim to the entire proceeds and recognised the wife’s 50% share in the circumstances of that case. Indian Kanoon
This is a useful warning: loan repayment records and legal title are not interchangeable.
Before signing the loan documents, coordinate the sale deed, ownership percentages, loan liability and intended tax treatment.
4. Adding Your Wife, Husband or Parents to Save Stamp Duty: Is It Always Beneficial?
Some Indian states provide stamp-duty concessions or other benefits for certain property transfers involving women, spouses or family members. This can make joint registration financially attractive.
However, stamp duty and registration charges are state-specific. The benefit may depend on the type of transaction, relationship between the parties, property location, applicable notification and whether the transaction is a purchase, gift or transfer.
For example, buyers in Punjab should not automatically assume that a concession available in Delhi, Haryana or Maharashtra applies to their transaction.
Punjab has also issued specific notifications concerning certain cooperative housing society transfers. A February 2026 Punjab Government notification discusses concessions for eligible transfers involving cooperative housing society members and specified family members. It is not a blanket concession for every ordinary property purchase in the state. avantiscdnprodstorage.blob.core.windows.net
Before adding a family member’s name solely to reduce registration costs, ask:
-
Does the applicable state notification cover this exact transaction?
-
Is the person being added a genuine co-owner?
-
What ownership percentage will they receive?
-
Will the additional owner have rights over sale proceeds and future appreciation?
-
What happens if the property is inherited, gifted or sold?
Saving a relatively small amount in stamp duty should not create a much larger ownership dispute in the future.
5. What Happens When One Co-owner Wants to Sell?
Imagine two siblings jointly own a residential property. After several years, one wants to sell because they need money, while the other wants to retain the house.
What happens?
A co-owner generally has rights in their own share, subject to the applicable law and the nature of the property. Section 44 of the Transfer of Property Act, 1882 addresses the transfer of a co-owner’s share and the rights acquired by the transferee. IndiaCode
But selling an undivided share is not the same as selling a separately demarcated apartment or portion of land.
A buyer acquiring an undivided share may become a co-owner and may face practical difficulties in possession, use or partition.
This can make an undivided share less attractive to prospective buyers.
For jointly owned residential property, it is sensible to agree in advance on:
-
Whether one co-owner can offer their share to an outsider.
-
Whether the other co-owner gets a first opportunity to purchase it.
-
How the property’s market value will be determined.
-
How sale proceeds and outstanding loan liabilities will be divided.
-
What happens if the co-owners cannot agree on a sale.
A properly drafted co-ownership agreement can help clarify these arrangements, although it cannot override mandatory law or replace the title documents.
6. Inheritance: What Happens If One Co-owner Dies?
Inheritance is where poorly planned joint ownership can create serious family disputes.
Suppose a husband and wife own a property in equal shares. The husband dies without making a Will.
Does the wife automatically become the sole owner of the entire property?
Not necessarily.
The wife’s existing 50% share remains hers. The deceased husband’s 50% share is dealt with under the applicable succession law, which depends on the deceased’s personal law, family circumstances and whether a valid Will exists.
For example, under the Hindu Succession Act, 1956, where a Hindu male dies intestate, his property generally devolves first upon the Class I heirs listed in the Act. Depending on the family structure, these can include his widow, children and mother. The exact shares must be calculated based on the heirs who survive him and the applicable statutory rules. Sci.gov.in
This means a deceased person’s mother may have a legal inheritance entitlement in the deceased person’s estate, including his share in a property, even if the property was purchased after marriage.
But this does not mean that a living mother automatically owns her son’s self-acquired property during his lifetime.
That distinction is essential.
Example: Husband, wife, children and mother
Assume a Hindu man owns a 50% share in a jointly registered apartment and dies intestate. He is survived by his wife, two children and mother.
Under the general Class I succession framework, his 50% interest would ordinarily be divided equally among these four heirs, assuming no other relevant facts alter the calculation.
Each would receive 12.5% of the entire apartment from his estate. The wife would also retain her original 50% ownership share.
This illustrates why buyers should plan inheritance rather than assume that joint registration automatically transfers the deceased person’s share to the surviving spouse.
A valid Will, properly prepared and executed, can help express the owner’s wishes, subject to applicable succession law and legal requirements.
7. The Benami Act: Is It Legal to Buy Property in Someone Else’s Name?
A common question is whether a person can legally pay for a property that is registered in their spouse’s name.
The Prohibition of Benami Property Transactions Act, 1988, as amended, generally restricts benami transactions and provides for consequences where property is held benami.
However, the legislation contains specific exceptions.
One important exception covers an individual purchasing property in the name of their spouse or child where the consideration is provided or paid from the individual’s known sources. The Act also contains a separate exception for certain purchases in the joint names of an individual and their brother, sister or lineal ascendant or descendant, subject to the statutory conditions. High Court of Tripura+1
This does not mean every arrangement involving another person’s name is automatically protected.
The source of funds, relationship, ownership documents, beneficial arrangements and statutory requirements matter.
There is another important distinction: an exception from the definition of a benami transaction does not automatically mean the person who paid the money has unrestricted rights to disregard the registered owner’s title.
For instance, a husband should not assume that because he funded a property registered in his wife’s name, he can later claim it as exclusively his.
The Supreme Court’s interpretation of the amended Benami Act and Section 4’s bar on enforcing rights in benami property makes it particularly important to obtain legal advice before structuring such a purchase. Sci.gov.in
Official reading: Prohibition of Benami Property Transactions Act, 1988 .
8. Tax Benefits: Does Joint Ownership Mean Double Tax Savings?
Joint ownership can be relevant for income-tax benefits, particularly where both co-owners are also co-borrowers and meet the applicable conditions.
However, simply adding another person’s name to the sale deed does not automatically create an additional tax deduction.
For eligible home-loan interest, Section 24(b) of the Income-tax Act provides for deduction subject to the applicable conditions and limits. Principal repayment may qualify under Section 80C under the old tax regime, subject to its conditions and overall limit.
The important point is that each claimant must satisfy the relevant ownership, borrowing and payment requirements. The tax position also depends on the tax regime selected and the nature and use of the property.
For a jointly owned and jointly financed home, the allocation of interest and principal should be supported by the actual loan documents, ownership structure and payment evidence.
Do not assume that two names on a property automatically mean both people can claim the maximum deductions.
Read the official provisions and current guidance from the Income Tax Department .
9. Five Common Joint Property Registration Mistakes
These are some of the most avoidable mistakes buyers make:
Mistake 1: Not specifying ownership percentages
Two people are named as buyers, but nobody clearly records their respective shares. This can lead to disputes when one wants to sell, partition or transfer their interest.
Mistake 2: Confusing a co-borrower with a co-owner
A person may be liable for a loan without necessarily having a corresponding ownership share. Always check both the loan agreement and sale deed.
Mistake 3: Paying from an undocumented source
Large cash payments, informal family transfers and undocumented contributions can create problems during tax scrutiny, ownership disputes and future resale.
Mistake 4: Assuming the EMI determines ownership
One person may pay the entire loan, but the registered ownership arrangement may be different. Do not assume that EMI contributions automatically change the shares recorded in the title documents.
Mistake 5: Ignoring inheritance planning
If one owner dies without a Will, their share may devolve under the applicable succession law. The surviving co-owner may not automatically receive the entire property.
10. A Practical Checklist Before Registering a Joint Property
Before signing a sale deed, use this checklist:
-
Identify every intended owner: Decide whose names should appear on the registered title.
-
Fix the ownership shares: Clearly specify 50:50, 70:30 or another agreed percentage.
-
Record contributions: Maintain bank statements and payment records for down payments and other purchase expenses.
-
Understand the home loan: Identify borrowers, co-borrowers, guarantors and their repayment obligations.
-
Coordinate the documents: Ensure that the sale deed, loan agreement and any co-ownership agreement are consistent.
-
Check the source of funds: Keep evidence of savings, loans, gifts and transfers.
-
Verify stamp duty: Check the applicable state rules and any genuine concession before adding another owner.
-
Plan inheritance: Consider a Will and review the succession consequences for each co-owner.
-
Agree on future sale arrangements: Decide how valuation, sale proceeds and exit from joint ownership will work.
-
Obtain independent legal advice: Have a property lawyer review the title and proposed ownership structure before registration.
A small amount spent on legal review before purchase can help prevent a much more expensive dispute later.
Conclusion: Your Money, Your Property—Make Sure the Documents Agree
Buying property is often one of the biggest financial decisions an Indian family makes. Yet many buyers spend more time negotiating the price than deciding how the property should legally be owned.
A husband may pay the entire EMI while his wife is a registered co-owner. A father may contribute the down payment while his children hold recorded ownership shares. Two siblings may purchase a property together without deciding what happens if one wants to sell.
These arrangements are not necessarily wrong. The problem arises when the financial understanding between family members does not match the legal documents.
Remember these three principles:
-
Payment is not automatically the same as legal title.
-
A home loan borrower is not automatically a property co-owner.
-
Joint ownership does not automatically mean equal ownership in every situation.
The Transfer of Property Act, the Benami Property Transactions Act, applicable succession laws, tax rules and state stamp-duty provisions all play different roles.
Before registering a property, decide who should own it, in what proportion, who will repay the loan and what should happen if an owner dies or wants to exit.
Do not wait for a family dispute to discover what your property documents actually say. Decide the ownership structure before you sign them.
At Bhumi Nivesh, we believe a smart property investment begins not just with choosing the right property, but also with understanding exactly what you are buying—and who legally owns it.
Frequently Asked Questions
1. If I pay 100% of the property price, can I register it in my wife’s name?
The Benami Property Transactions Act contains an exception for certain purchases in a spouse’s name using the individual’s known sources of funds. However, this does not mean the person paying can automatically disregard the wife’s registered ownership. Obtain legal and tax advice before proceeding.
2. If my name is on the home loan, am I automatically a co-owner?
No. Being a borrower or co-borrower does not automatically establish ownership. Check the registered title documents.
3. Can a co-owner own 70% while another owns 30%?
Yes, ownership can be structured in different proportions, subject to applicable law and proper documentation. The intended shares should be clearly recorded in the transaction documents.
4. If my husband pays all the EMIs, can he claim the entire property?
Not automatically. EMI payments alone do not necessarily alter the ownership shares recorded in the title documents.
5. Does a mother have an automatic right over her married son’s self-acquired property?
No. A mother does not automatically become a co-owner of her adult son’s self-acquired property during his lifetime merely because she is his mother. Inheritance rights may arise if he dies, depending on the applicable succession law and whether he leaves a valid Will.
6. If one joint owner dies, does the surviving owner automatically get the whole property?
Not necessarily. The deceased owner’s share generally devolves according to the applicable succession law or valid testamentary arrangements. The other co-owner retains their own existing share.
7. Can I remove another person’s name from a jointly registered property?
Not simply by requesting a change. A legally valid transfer, release, gift, sale, partition or other appropriate instrument may be required, depending on the circumstances and applicable law.
Sources and Further Reading
1. Transfer of Property Act, 1882 — Section 45: Joint Transfer for Consideration — explains how interests may be determined when two or more people purchase property together. IndiaCode
2. Transfer of Property Act, 1882 — Section 44: Transfer by One Co-owner — addresses the rights associated with transferring a co-owner’s share. IndiaCode
3. Supreme Court of India — Judgment dated 15 May 2024 — Benami Act provisions and restrictions on enforcing claims to benami property. Sci.gov.in
4. Prohibition of Benami Property Transactions Act, 1988 — statutory framework and exceptions. High Court of Tripura
5. Sangeeta Gera v. Sanjeev Gera, 22 September 2025 — Delhi High Court decision concerning ownership claims in jointly held property. Indian Kanoon
6. Hindu Succession Act, 1956 — India Code — consult the Act’s provisions concerning intestate succession and Class I heirs.
7. Income Tax Department of India — current tax provisions and home-loan deduction guidance.
8. Punjab Government notification dated 2 February 2026 — specific cooperative housing society transfer concessions in Punjab. avantiscdnprodstorage.blob.core.windows.net
Legal disclaimer: This article is for general awareness and educational purposes, not individual legal or tax advice. Property rights, stamp duty, tax deductions and inheritance depend on the transaction documents, personal law, state rules and facts. Have a qualified property lawyer and tax professional review your particular transaction before registration.
